As we continue our discussion about social inflation, we must recognize its broader effects. These effects exceed the headline jury awards we hear about.
The quick review: Social inflation refers to the rising costs of insurance claims that exceed general economic inflation. Several factors influence it. These include increased litigation, higher jury awards, expanded definitions of liability, and changing expectations around compensation.
Nuclear verdicts, generally defined as jury awards exceeding $10 million, contribute to this growing concern. They are only part of the story.
But let’s take a look at another piece of the pie. An insurance company pays 100 separate claims, each resulting in a $1 million payout. That’s $100 million in claims paid. None of those claims required a nuclear verdict to impact the insurer financially. The total effect came from many settlements, not from one extraordinary verdict.
It’s the accumulation of increasingly expensive claims, along with the cost of defending them, that puts pressure on insurers. When claim costs consistently rise, insurance companies must account for those losses when evaluating their overall risk, setting rates and determining the cost of providing coverage.
Another factor contributing to the changing claims environment is the use of policy-limits demands. In serious accident cases, a plaintiff’s attorney may approach the insurance company early in the claims process with a demand to settle for the full amount of the available liability coverage.
Sometimes these demands come with a strict deadline, requiring the insurer to evaluate the claim and make a decision within a limited timeframe. If the insurer does not accept the demand and the case proceeds to trial, a jury could ultimately award damages that exceed the available policy limits.
The difference could leave the insured business facing significant financial exposure. This creates a difficult balancing act for insurers: evaluating the claim, determining the appropriate settlement value, protecting their policyholder’s interests, and making decisions in an increasingly challenging litigation environment.
What Is Happening in Commercial Auto?
A recent AM Best report notes rising claim costs. Commercial auto liability insurance continues to feel the impact.
Between 2014 and 2024, general economic inflation averaged 2.8% annually. During that same period, commercial auto liability loss payments during the first 12 months of a claim increased at an average annual rate of 6.4%. That’s more than twice the rate of general inflation. ¹
These numbers help explain why commercial auto insurance has become increasingly challenging for both insurance companies and the businesses they insure.
And while the largest jury awards certainly make headlines, a business doesn’t have to experience a nuclear verdict to face a substantial financial loss.
In 2024, the median nuclear verdict against corporate defendants reached $51 million, according to Marathon Strategies. While that number illustrates the extraordinary size of some jury awards, it represents the median of nuclear verdicts across industries, not the typical commercial auto claim.²
The more immediate concern for many businesses may be the serious claims that never make the headlines but still result in settlements or judgments exceeding $1 million.
What Does This Mean for Your Business?
Let’s put this into perspective.
A $1 million commercial auto liability limit may sound like too much coverage. But consider this hypothetical situation here in Maine.
Imagine one of your employees is driving a company pickup truck to a job site and is involved in a serious accident. Another driver suffers life-altering injuries, requiring extensive medical treatment, ongoing rehabilitation and potentially a lifetime of care.
The resulting claim could include medical expenses, lost income, future earning capacity, pain and suffering, and other damages.
Now imagine the claim ultimately results in a $1,000,000 settlement.
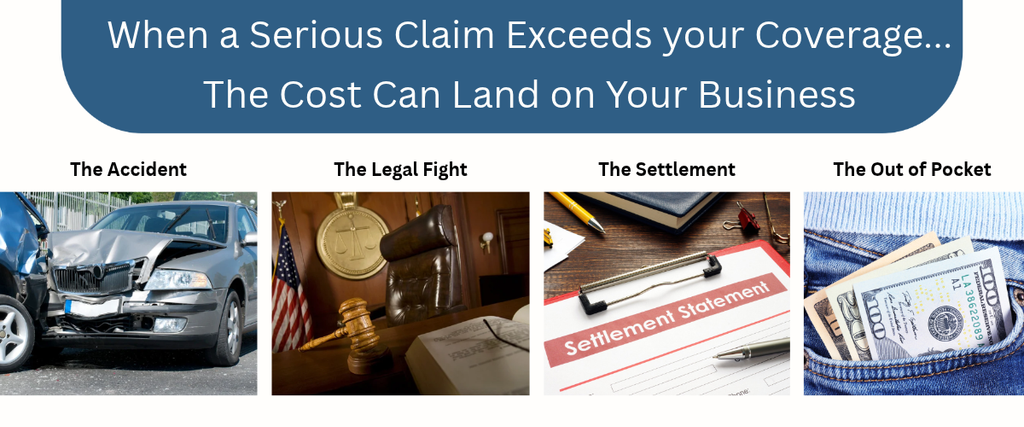
If your business has a $500,000 commercial auto liability limit, that could lead to a $500,000 difference. This is the gap between the policy limit and the settlement amount. Without the increased liability limit to the max of $1,000,000.00, your business or you personally (depending how your business is structured) would be responsible for the $500,000.00 difference.
This isn’t a nuclear verdict. It’s a hypothetical example of how a serious accident can create financial exposure without ever reaching the multi-million-dollar jury awards we read about in the news.
And that’s why the limits you carry deserve a closer look.
Is Your Business Protected?
This is why having a conversation with your independent insurance agent is so important.
Your commercial auto policy should be reviewed to determine whether your liability limits adequately reflect your business operations, the vehicles you operate, and the potential risks you face.
Adequate liability coverage isn’t just about protecting your business. It’s about taking responsibility for the people who could be affected by your business.
It may also be worth discussing with your agent an umbrella policy, which can provide an additional layer of liability protection above certain underlying policies, subject to its terms and conditions.
A million dollars is still a substantial amount of money. But in today’s litigation environment, it may not go as far as you think. It is easy to think that $ 1 Million dollars too much for liability coverage. But just stop a minute and think if you were on the other side of the coin. What kind of coverage are you hoping the other guy has to protect your financial future.
At Cheney Insurance, we try to protect your business by looking beyond today’s premium. We also understand the financial risks that could affect your future.
Let’s start a conversation today.
It’s Your Business. Let’s Protect It.
¹ AM Best, Best’s Special Report: Social Inflation Adds Pressure to US Property/Casualty Liability Results, October 2026.
² Marathon Strategies, Corporate Verdicts Go Thermonuclear, March 2025 report covering 2024 corporate jury verdicts.
Editorial note: The 1,00,000.00 settlement is a hypothetical illustration, not an actual Maine claim or an estimate of typical settlement amounts. The amount above the policy limit is not necessarily the amount the business would ultimately pay; applicable policy terms, other insurance, legal defenses and settlement circumstances matter.
Heather McKenna
Commercial Producer / Marketing
heathermckenna@cheneycompanies.com
Cheney Insurance- It’s Your Life – Lets’ Protect It