Social Inflation: Higher Awards, Higher Premiums

Social inflation and rising jury awards contributing to higher insurance costs.

Discover how social inflation, rising jury awards, and increasing lawsuit costs are affecting commercial insurance premiums and businesses.

When we hear the word inflation, most of us first think of day-to-day cost. Groceries, gas, building materials, vehicle repairs, and just about everything else. There is another type of inflation affecting businesses and the insurance industry. It does not appear on a grocery receipt, yet it is affecting our insurance premiums.

It’s called Social Inflation, and it is having a growing impact on the cost of liability claim. It is seen particularly in commercial auto insurance.

What Is Social Inflation?

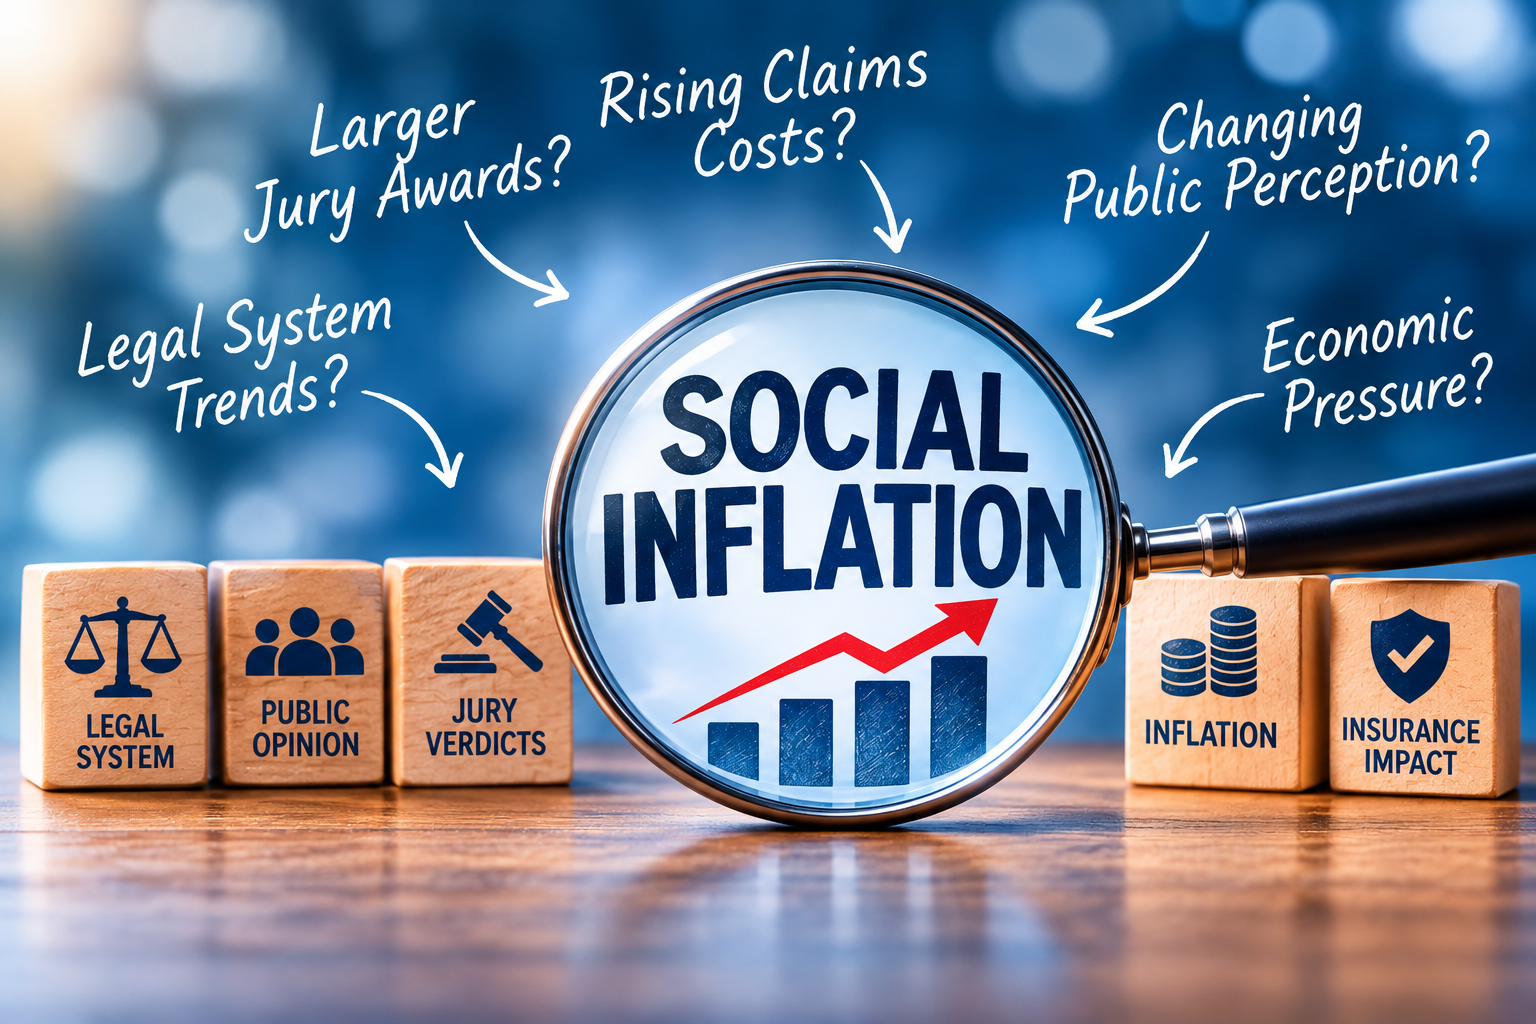
Social inflation refers to the rising costs of insurance claims and lawsuits that go beyond what we would typically expect from standard economic inflation.

Social inflation is influenced by factors such as larger jury awards, changing public attitudes toward businesses and corporations, and the increasing willingness of juries to hold companies financially responsible for accidents and injuries.

In simple terms, claims are becoming more expensive not just because medical bills, vehicle repairs, and other costs are increasing, but because the amounts awarded in lawsuits are increasing.

And some of those numbers are staggering.
When Jury Awards Become Nuclear

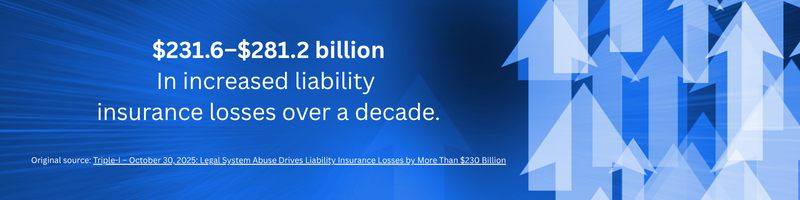
A nuclear verdict generally refers to a jury award of $10 million or more. When awards reach $100 million or higher, they are often referred to as mega-nuclear verdicts.

These aren’t simply larger settlements to cover medical expenses, lost wages, or property damage. They can include substantial amounts for pain and suffering, emotional distress, and punitive damages intended to punish a defendant for its conduct.

For businesses, particularly those operating commercial vehicles, the financial consequences can be enormous.

Consider a commercial truck involved in an accident. Beyond the actual damages and medical expenses, a lawsuit may focus on the company’s hiring practices, driver training, vehicle maintenance records, safety policies, and what the company could or should have done differently.

The conversation can quickly shift from the accident itself to the company’s overall responsibility.

Why Are Jury Awards Getting Larger?

There isn’t one single reason for the increase in social inflation. Several factors are contributing, including changing attitudes toward large corporations and how juries view corporate responsibility when there are claims.

Over the years, public perception of large businesses has evolved. Some jurors may enter a courtroom with the belief that large corporations have significant financial resources and should be held to a higher standard of accountability.

In some cases, the focus shifts beyond what a company actually did or didn’t do at the time of an accident. Instead, jurors may begin considering what the company should have done to prevent the situation from happening in the first place.

Was the driver properly trained? Were safety procedures followed? Were maintenance concerns addressed? Could the company have done more?

These questions can influence how jurors assign responsibility and determine the financial consequences.

And when a jury believes a company failed to take reasonable precautions, the resulting award can extend far beyond the original cost of the accident.

The Power of Anchoring: Putting a Number in the Jury’s Mind

Another factor receiving attention in discussions about social inflation is a legal strategy known as anchoring.

Anchoring occurs when an initial number is introduced during a discussion or negotiation, influencing how people perceive the value of everything that follows.In a courtroom, plaintiff attorneys may present a very large dollar amount early in a trial when explaining the damages they believe their client deserves.

Even if that number seems extraordinarily high, it can become a reference point in the minds of jurors. As they begin discussing the case and considering damages, that initial figure may influence what they consider a reasonable award.

For example, if an attorney suggests that a case is worth $50 million, jurors may begin evaluating the damages with that number in mind rather than starting from zero.This doesn’t mean juries automatically award the amount requested. However, the initial figure can influence their perception of what an appropriate award might look like.

When combined with emotional testimony, the severity of an injury, and questions about corporate responsibility, anchoring can contribute to increasingly large jury awards.

What Does This Mean for Businesses?

Social inflation is changing the liability landscape. Businesses are facing exposure that goes beyond the traditional costs associated with accidents and injuries.

For companies with commercial vehicles on the road, this is particularly important. A single accident can potentially result in a lawsuit involving not only the driver but also the business that owns or operates the vehicle.

And as jury awards continue to grow, the insurance industry must account for the potential cost of these claims when evaluating risk, setting premiums, and determining coverage limits.

The bottom line? Standard inflation isn’t the only thing driving up the cost of doing business. Social inflation is adding another layer of financial exposure, and understanding it is an important part of protecting your business.

Stay tuned for Part 2, where we’ll look at how social inflation is affecting commercial auto insurance, why liability limits matter more than ever, and what business owners can do to help protect themselves.

Source: Insurance Information Institute
Heather McKenna

Commercial Producer / Marketing

heathermckenna@cheneycompanies.com

Cheney Insurance- It’s Your Life – Let’s Protect It
Seafood Spoilage and Refrigeration Breakdowns: Coverage for Fish Markets and Processors

From lobster pounds and fish markets to seafood processors and waterfront restaurants, midcoast Maine businesses depend on refrigeration, freezers, and holding tanks every day. When a compressor fails or a winter storm knocks out power, product can be lost in hours. The way your policy responds often depends on what kind of operation you run and what caused the loss.

Lobster Pounds and Holding Tanks

Live product brings its own set of risks. Pumps, oxygen systems, and water temperature controls all have to work around the clock, and a failure overnight can be costly by morning. Some commercial property policies treat live animals differently from frozen or refrigerated inventory, and some limit or exclude them entirely. Ask how your policy treats tanks, pumps, and the product inside them.

Fish Markets and Restaurants

For markets and restaurants, spoilage coverage is usually the key piece. It’s often added by endorsement and can respond when product spoils because of a power failure or equipment breakdown on your premises. Outages that start off your premises, such as a utility line going down in a storm, may require separate utility service interruption coverage.

Seafood Processors

Processors often rely on large walk-in coolers, blast freezers, and specialized machinery. Equipment breakdown coverage can help repair or replace that machinery after a sudden mechanical or electrical failure, and many versions include some spoilage protection. Business income coverage may also help if a covered loss shuts down production, subject to waiting periods and policy terms.

Matching Limits to the Busy Season

Inventory swells during summer and around the holidays. A spoilage limit set during a slower month may fall short when every cooler is full, so review limits before peak season.

A Few Habits That Help

  • Install temperature alarms that alert you after hours
  • Test backup generators regularly
  • Keep refrigeration service records and inventory logs

Cheney Insurance in Damariscotta, ME can review your commercial property insurance for spoilage and equipment breakdown gaps. Policy terms vary. Seafood businesses across Damariscotta, ME and the midcoast can reach out to Cheney Insurance or learn about our restaurant insurance options.

From Insurance Agent to Client: The Ultimate Customer Service Lesson


Suddenly, I Was the Client: A Reminder of Why Customer Service Matters

As insurance agents, we spend our days helping people protect their homes, vehicles, businesses, and the things that matter most to them. We review policies, explain coverage, answer questions, process payments, and reach out to clients when renewal time approaches. But sometimes, we get so caught up in the business of insurance that we forget what the experience feels like on the other side of the desk where customer service is important.

Recently, I was reminded of just how important that experience is.

Suddenly, I Was the Client

As an insurance agent, I have an advantage when reviewing our personal policies. I understand the terminology, know what questions to ask, and have a better idea of how insurance companies and agencies operate. I understand what is happening in the industry that can help explain and justify a premium or rate increase, as well as how I can explore options to lower my premium.

So, when we purchased a second home in Florida last year, I knew the questions to ask, but I was also learning about a new insurance market. Requirements for quotes, limits, and coverage’s can vary from state to state because insurance is overseen and governed by individual states, not the federal government. We secured what we thought was a reasonable premium for the individual home and flood insurance policies and went about enjoying our new home.

Nearly a year later, an email arrived from our flood insurance company just 13 days before the renewal date.

Payment due: 92% increase in premium.

Wait. What?

A 92% increase! Quite a bit of sticker shock. But even more shocking was that there had been no phone call from our agent or anyone in the agency to explain the increase, discuss what had changed, offer other options, or simply check in with us.

As an insurance professional, I understand that premiums can change for various reasons, such as the cost to rebuild, the overall increase in lawsuits, and, yes, natural disasters. I wasn’t expecting someone to magically make the cost of insurance disappear. But what I was expecting was communication.

And just like that, I wasn’t the insurance agent anymore. I was the frustrated homeowner trying to understand what had happened and what other options we had. Not just an email telling us to “make a payment.” I was not impressed with this customer service.

When Getting Answers Becomes a Job of Its Own

I did what many clients do when they receive an unexpected bill: I picked up the phone and let my fingers do the walking.

After listening to all the number options, I chose one and was placed on hold. Then came the offer to use a virtual assistant. I wanted a person. I kept saying, “Customer representative,” but the virtual assistant wasn’t listening. Back on hold I went, listening to elevator music interrupted every 10 seconds by a message saying, “We apologize for the delay. We understand your call is important. Please wait on the line for the next available representative.”

Finally, I was transferred to the appropriate department. After gathering all my information to access the account, the call was disconnected.

Sigh.

At that point, I had two choices: spend another 15 minutes trying to get through the system or find another way forward.

I chose to move forward.

I sat behind the keyboard and started researching other insurance agencies in our area. I scoured websites, social media, and reviews, and even used AI. A couple of agencies stood out, so I jumped in the car, programmed the map, and started my client journey. After a couple of stops and a fresh cup of coffee, I eventually walked into an office that instantly gave me that Cheney Insurance feel.

A Welcome Change

From the moment I entered the office, the experience felt familiar. The receptionist greeted me warmly, asked how she could help, and invited me to have a seat, explaining that an agent would be with me shortly. As I sat in the lobby, which was adorned with Halloween decor, I could hear her friendly tone continue every time she picked up the constantly ringing phone.

Within minutes, a Personal Lines agent came out from behind the receptionist’s desk, smiled, extended her hand, introduced herself, and welcomed me into her office.

I’ll admit, one of the first things I noticed was how clean and organized her desk was. It made me think that perhaps I had a little work to do on my own desk! But what stood out most wasn’t the office. It was the attention that she was giving me the potential client.

I explained upfront that, while I was an insurance agent myself, I wasn’t there to tell her how to do her job or brag about what I thought I knew about insurance. I was there to interview her and her company, and then listen.

I had questions. How did the agency operate? Who would we be dealing with throughout the policy term? Would someone stay in contact with us? Was there online access to our policies? How would we file a claim? And, most importantly, if we had a question or concern, would we be able to reach someone who could help?

She listened. She didn’t spend our meeting peering down at her phone when it lit up or dividing her attention between me and her computer.

She answered my questions, explained the process, and gave me a clear understanding of what I could expect.

As our conversation continued, I found myself relaxing back in my chair. I was beginning to feel confident that I had found an agency that valued the relationship as much as the business.

I finally said, “Okay, let’s see what you can offer us.”

It’s the Little Things That Make a Difference

We reviewed the home information for the flood policy, and she quickly entered the details into her computer. Within about 15 minutes, the printer was running, and I had two flood quotes in front of me to review. What impressed me was that she took the time to review the quotes as if I had no knowledge of insurance. She treated me as a client.

When I looked down at the quotes, they were both lower than the premium I walked in with, and while offering the same coverage’s as my current policy. The good feeling was getting even better.

Naturally, I said next, “Okay, let’s see what you can do for the home!”

We continued our conversation, discussed the additional information she needed for the home quote, and identified a few questions that would require me to gather details once I returned home. I thanked her for her time and told her I looked forward to building a relationship with the agency. Having someone right down the road was an added bonus.

As I walked back through the lobby, the receptionist thanked me for stopping in and wished me a blessed day.

And I left feeling good about the experience.

Once home, I sent the additional information she had requested, and 20 minutes later, there was a proposal in my inbox. I was again pleased with the proposal, as she was able to add additional credits that hadn’t been included before. She followed up with a phone call, asked if I had any questions, and whether I would like to move forward.

Yes, please!

And just like that, a new relationship was formed.

A Reminder of Why Customer Service Matters

As an insurance agent, I know how important it is to stay connected with our clients. Sometimes, a renewal conversation is about more than a policy. It’s about asking how the kids are doing, hearing about a family visit, or telling them what a great meal you had at their restaurant last weekend.

Those little moments build relationships, and my recent experience reminded me how much they matter.

I walked into that Florida agency worried that, in today’s world of technology, I wouldn’t find what we offer at Cheney what is important to us at Cheney Insurance- customer service. However, I left feeling confident that I had found people I could work with and a team that valued my business. That feeling came from something simple: someone took the time to listen, answer my questions, and make me feel welcome.

It was a good reminder that while we can’t always control insurance premiums, we can control how we treat people along the way.

And sometimes, being on the other side of the desk is exactly what we need to appreciate that.

Heather McKenna

Commercial Producer / Marketing

heathermckenna@cheneycompanies.com

Pumpkinfest Weekend Guests and Your Home Liability

Every October, Damariscotta goes gloriously pumpkin-crazy. Giant gourds get carved into works of art, hollowed-out pumpkins become boats paddling across the harbor, and visitors pour into town for Pumpkinfest and Regatta. For plenty of locals, that also means a full house: friends on the couch, relatives in the spare room, and a driveway packed with cars. It’s one of the best weekends of the year, and a good time to think about what happens if a guest gets hurt at your place.

🎃 The Front Step Factor

Most guest injuries at home aren’t dramatic. They’re slips on wet leaves, stumbles on dim porch stairs, or a trip over a stray boot. If a guest is injured and you’re found responsible, the personal liability portion of your homeowners policy is typically what responds.

🎃 The Quick-Fix Coverage Many People Forget

Many home policies include medical payments to others, which can help with a guest’s minor medical bills regardless of who was at fault. It’s designed for small, everyday mishaps and can keep a sprained ankle from turning into a bigger dispute.

🎃 Cider, Cocktails, and Common Sense

If drinks are part of the celebration, keep an eye on your guests. Maine law can hold hosts responsible in certain circumstances when alcohol is served to someone visibly intoxicated or to anyone under 21. Having a plan for rides home is always a smart move.

🎃 Charging Guests Changes the Picture

Hosting friends for free is very different from renting a room to festival visitors. If money changes hands, your homeowners policy may not respond the same way, so talk with your agent before listing space for the weekend.

A Host’s Pre-Festival Checklist

  • Rake leaves and clear walkways and steps
  • Check that porch and outdoor lights work
  • Secure pets who may not love a crowd
  • Know your liability limits, and whether an umbrella policy sits above them

Cheney Insurance has been part of the Damariscotta community since 1954, and we love Pumpkinfest as much as anyone. Learn more about our home insurance options, read our story, or stop by Cheney Insurance on Main Street in Damariscotta, ME before the pumpkins hit the water.